


Delaware Shareholder Recovery 101: Class Actions vs. Appraisal Rights
Appraisal rights are at the center of a September 2026 suit in which Endeavor Group and Silver Lake moved to block appraisal claims on Endeavor shares worth $4.1 billion at the $27.50 deal price. Appraisal rights are a stockholder’s statutory right under DGCL Section 262 to have the Delaware Court of Chancery set the fair value of shares in a merger instead of accepting the merger price. Investors must act before the deal closes, unlike Delaware fiduciary class actions, which pay holders automatically.
What are appraisal rights?
Appraisal rights are a stockholder’s legal right to have a court decide what its shares were worth in a merger, instead of accepting the price the buyer paid. In Delaware the right comes from Section 262 of the Delaware General Corporation Law (DGCL 262), the statute that sets who may seek appraisal, how to demand it and how the Court of Chancery values the shares. A stockholder who does not vote for the deal, delivers a written demand on time and holds its shares through the merger’s effective date is entitled to an appraisal by the Court of Chancery of the “fair value” of its shares. The court sets that value “exclusive of any element of value arising from the accomplishment or expectation of the merger” and takes into account all relevant factors. Unless the court decides otherwise, interest accrues from the closing at 5% over the Federal Reserve discount rate, compounded quarterly. In simple terms, appraisal rights let dissenting stockholders swap the deal price for a court-determined fair value, which can come out higher or lower.
Why Delaware matters for shareholder recovery
Delaware’s status as the legal home of choice for U.S. corporations drew headlines in February 2024 when business magnate Elon Musk relocated SpaceX and Neuralink to Texas and Nevada, respectively. Public dialogue quickly raised questions about whether other high-profile companies might follow suit. Tesla moved its incorporation to Texas in June 2024. Delaware responded in March 2025 with Senate Bill 21 (see below). The state of incorporation matters for shareholder recovery because its law governs the appraisal and fiduciary claims available after a merger.
There has been no mass corporate exodus from Delaware: over two-thirds of the Fortune 500 still call it their corporate home, according to the Delaware Division of Corporations. The First State remains a crucial forum for protecting investor interests, as its Court of Chancery holds jurisdiction over complex corporate transactions and high-stakes legal disputes.
Delaware law is particularly relevant to shareholders when merger payments do not fully reflect an issuer’s fair value. In December 2024, for example, a landmark $1 billion settlement related to Dell Technologies’ 2018 stock swap deal paid out to minority shareholders. Similar cases involving Paramount Global ($122.5 million, approved July 2023) and Pattern Energy Group ($100 million, approved May 2024) resulted in class action settlements. In October 2026 the Court of Chancery approved a $250 million Activision Blizzard settlement over Microsoft’s acquisition.
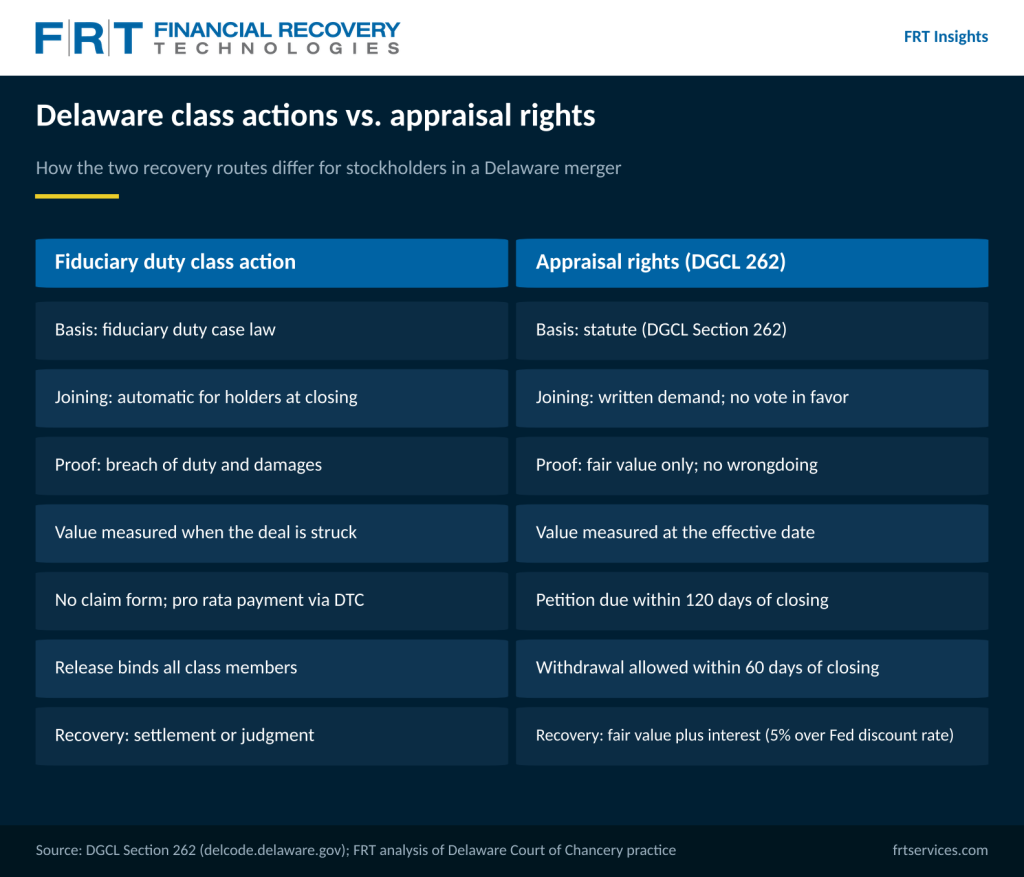
In these situations, investors have two primary legal mechanisms for seeking compensation: breach of fiduciary duty cases and appraisal rights matters. Below, we explore the differences between these actions and their implications for investors. In short, a Delaware fiduciary duty class action includes holders automatically and requires proof of wrongdoing, while appraisal rights require a timely demand and ask the court only to set fair value.
High-level considerations for investors
Breach of fiduciary duty cases:
- A specialized class action filed in Delaware Chancery court
- Investors are not required to submit proof of claim forms to receive compensation
- Those giving shares in the transaction are automatically eligible
- These cases are relatively common, with roughly two dozen settlements a year in FRT’s tracking
Appraisal rights opportunities:
- A representative proceeding focused on a Delaware merger’s valuation
- Investors must affirmatively exercise their appraisal rights to participate
- Shares must be held continuously through the merger’s effective date; the appraisal claim then runs to case resolution
- These actions can still be large for investors who join: dissenting Endeavor shares were worth $4.1 billion at the deal price
Key challenge: Investors must carefully review any deal announcement by the issuer and determine whether to challenge the valuation before the appraisal demand deadline in DGCL 262(d). When a merger goes to a stockholder vote, the company must give notice at least 20 days before the meeting and the written demand must be delivered before the vote. When a merger is approved by written consent, as a short-form merger or after a tender offer under Section 251(h), the demand is due within 20 days after notice is given (for a tender offer, by the later of the offer closing and that 20-day date).
Who has appraisal rights under DGCL Section 262?
Under DGCL 262, appraisal rights belong to stockholders of a Delaware corporation in most mergers and consolidations who did not vote in favor of the deal or consent to it in writing. Record holders can demand appraisal. Since August 2022, beneficial owners holding through a broker or custodian can also demand in their own name if they identify the record holder and supply evidence of ownership. Rights are generally not available for shares listed on a national securities exchange or held by more than 2,000 holders, unless holders must take cash or other consideration besides listed stock. That exception is why appraisal rights arise mainly in cash deals and take-privates. For listed shares, the court dismisses the case unless the dissenting shares exceed 1% of the class or $1 million in deal value. A company can also grant appraisal rights in its charter for asset sales or charter amendments.
How do investors exercise appraisal rights?
Exercising appraisal rights in Delaware under DGCL 262 takes four steps, each with a fixed deadline. First, the investor must not vote for the merger; a vote against or a proxy does not count as a demand. Second, it must deliver a written appraisal demand on time, as described above. Third, it must hold the shares continuously through the merger’s effective date. Fourth, the company or any qualifying stockholder may file an appraisal petition in the Delaware Court of Chancery within 120 days after the effective date. An investor that has not filed or joined as a named party may withdraw its demand and take the deal price within 60 days after the effective date. After that, it waits for the court’s fair value ruling or a negotiated settlement, while the company may prepay cash to limit interest.
Breach of Fiduciary Duty Basics
Breach of fiduciary duty claims challenge the process by which a merger agreement came together, alleging that one or multiple parties failed to act in shareholders’ best interests, and that they received too little consideration as a result.
Procedurally, these cases mirror standard U.S. securities class actions filed in federal court, meaning all eligible claims are automatically included (unless they opt out). However, unlike federal proceedings, Delaware’s class action settlements are distributed to those who previously tendered their shares, eliminating the need for them to provide proof of claim forms. Investors holding eligible securities when the transaction is effective and shares are tendered are automatically included in the class, with settlements distributed pro rata based on individual holdings at the time.
Settlement administrators directly credit the shareholders of record, with custodians holding shares in street name and allocating funds to the actual beneficial owners. While this approach reduces the administrative cost and burden otherwise borne by investors in most class actions, the custodians vary in the form and timing of their notification and remittance procedures. This can lead to unexpected distributions for custodial clients who are not diligently monitoring these cases and do not know the money is coming, particularly if they must further remit funds to their own customers.
Related: How securities class action payouts work in Delaware’s Court of Chancery
A closer look at appraisal opportunities
Appraisal opportunities are a more selective legal mechanism for shareholders seeking additional value in a Delaware-based transaction. To be eligible for an appraisal action, investors must give notice that they intend to exercise their rights and then hold their shares through the merger’s effective date.
Appraisal opportunities do not allege wrongdoing related to deal conception and construction. Rather, they focus on an investor’s right to a fair, objective determination of the value of its investment. Both investors and the transacting parties bear equal burden to demonstrate “fair value” through the evidence.
While both fiduciary duty and appraisal claims involve disputes over the sufficiency of deal consideration, that value is measured at different times. For class actions, the value is determined when the deal is struck. Subsequent price movements do not impact class claims. For appraisal, it’s measured at deal closing, the merger’s effective date (DGCL 262(h); In re Appraisal of PetSmart). Thus, price increases between deal conception and closing can strengthen appraisal claims, while price declines can weaken them.
Like class actions, appraisal proceedings are pursued by a representative shareholder. However, because appraisal rights must be actively exercised, only those that do so are included. This is similar to the opt-in approach to group litigation we often see outside the U.S.
Appointing lead counsel in the Endeavor appraisal, Vice Chancellor Lori W. Will drew the line plainly:
“But appraisal suits are not class actions; there is no class for the court to certify.”
Lori W. Will, Vice Chancellor, Delaware Court of Chancery. Letter opinion, In re Appraisal of Endeavor Group Holdings, Inc., C.A. No. 2025-0317-LWW, Jul 2025
The court can still appoint lead counsel to represent the dissenting stockholders, which is why only investors who perfected their rights share in the result.
When another investor initiates and successfully prosecutes the appraisal petition, shareholders that have exercised their appraisal rights can share in any premium resulting from those efforts, which are then decided either by the court or through direct negotiations.
Special situations: Endeavor
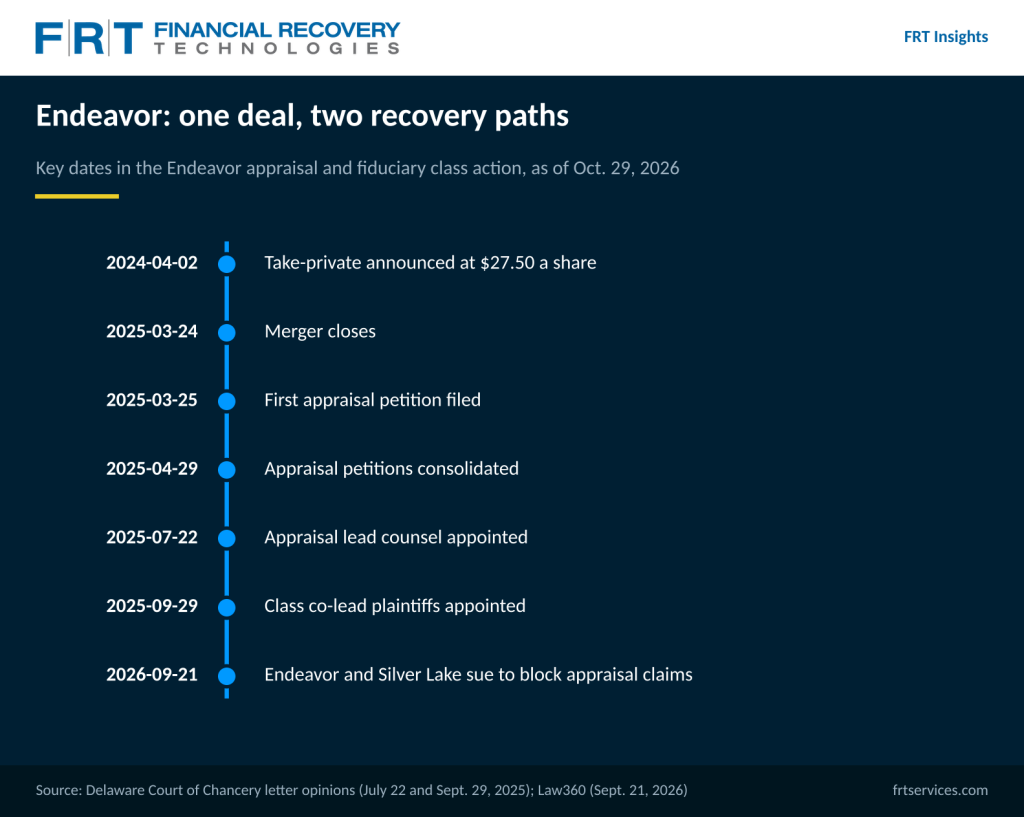
A single transaction can give rise to both types of claims discussed above. One recent example is Silver Lake’s $13 billion take-private of Endeavor Group Holdings, which closed on March 24, 2025 and drew both appraisal petitions and a fiduciary duty class action.
The deal, which provided $27.50 per share to investors, saw Endeavor’s management team and Silver Lake shareholders roll over their equity rather than redeeming at the $27.50 merger price. As a result, the Endeavor scenario presented investors with a potentially mutually exclusive decision: they could pursue either the appraisal or the class action, but likely not both. Investors generally cannot pursue both appraisal and a Delaware class action for the same shares, because appraisal claimants give up the merger price that class settlements are paid on.
As of Oct. 29, 2026, both paths remain in litigation. The first appraisal petition was filed the day after closing. The court consolidated the petitions in April 2025. Dissenting shares total 149.3 million, worth $4.1 billion at the deal price. Separately, a fiduciary duty class action led by Icahn Enterprises and Handelsbanken alleges that insiders and Silver Lake breached their duties; the court appointed those funds co-lead plaintiffs in September 2025. In September 2026, Endeavor and Silver Lake sued dozens of hedge funds in the Court of Chancery to bar appraisal claims on shares bought after the deal was announced. How the court rules will shape whether Endeavor appraisal claimants recover a premium and whether post-announcement buyers remain eligible in future deals.
FRT advises clients on the benefits, risks and recovery implications of appraisal opportunities such as Endeavor, including whether to demand appraisal or stay in a related class action.
How SB 21 changed the class action and appraisal choice
Delaware’s Senate Bill 21 became law on March 25, 2025 and changed both sides of the comparison above. For fiduciary duty class actions, it set a one-third ownership floor for treating a stockholder as a controller, expanded safe harbors for conflicted transactions and narrowed Section 220 books and records demands, which plaintiffs use to build these cases. SB 21 did not amend DGCL 262, so appraisal rights work as before. As FRT noted in Pendulums: The Impact of SB21 on Delaware Securities Class Actions, narrowing the class action route may push more investors toward appraisal. The Endeavor dispute is an early test of that shift. For institutions, SB 21 makes the appraisal decision at deal announcement more important, since a later class action may be harder to bring.
As Delaware shareholder recovery evolves, a set of timeless principles still applies for investors and fiduciaries in this venue: stay vigilant, stay informed and consult experts as necessary.
This page is reviewed quarterly and after major rulings in the Endeavor appraisal or class action. Next scheduled review: January 29, 2027.
Frequently asked questions
Who has appraisal rights?
In Delaware, appraisal rights belong to stockholders who do not vote for a qualifying merger, make a timely written demand and hold their shares through the effective date. Beneficial owners can demand in their own name. Shares listed on an exchange generally have appraisal rights only when holders must take cash or other non-stock consideration.
What are appraisal rights in simple terms?
Appraisal rights let a stockholder who disagrees with a merger price ask a court to decide what the shares were worth. The stockholder then receives that fair value plus interest instead of the deal price, which may be more or less.
What is DGCL Section 262?
DGCL Section 262 is the appraisal rights section of the Delaware General Corporation Law. It sets which mergers carry appraisal rights, who can demand appraisal, the demand and petition deadlines and how the Court of Chancery values shares and awards interest.
What is the 20-day deadline for appraisal rights?
The 20-day deadline for appraisal rights comes from DGCL 262(d). A company putting a merger to a stockholder vote must send appraisal notice at least 20 days before the meeting. Demands are due before the vote. For short-form, written-consent and tender offer mergers, appraisal demands are due within 20 days after the notice is given.
Can an investor pursue both appraisal rights and a Delaware class action?
Usually not in practice. Appraisal claimants give up the merger consideration for a court valuation, while class settlements generally pay holders who took that consideration. Endeavor investors faced this choice in 2025.
A deeper discussion on Delaware
FRT’s January 2025 Market Insider session covered Delaware recovery trends and is available on demand. For current data on Delaware fiduciary duty settlements and other no claim form cases, see FRT’s 2026 Class Action Intelligence Report.